Lukki Verification: KYC Documents and First Cashout
 Available in US
Content
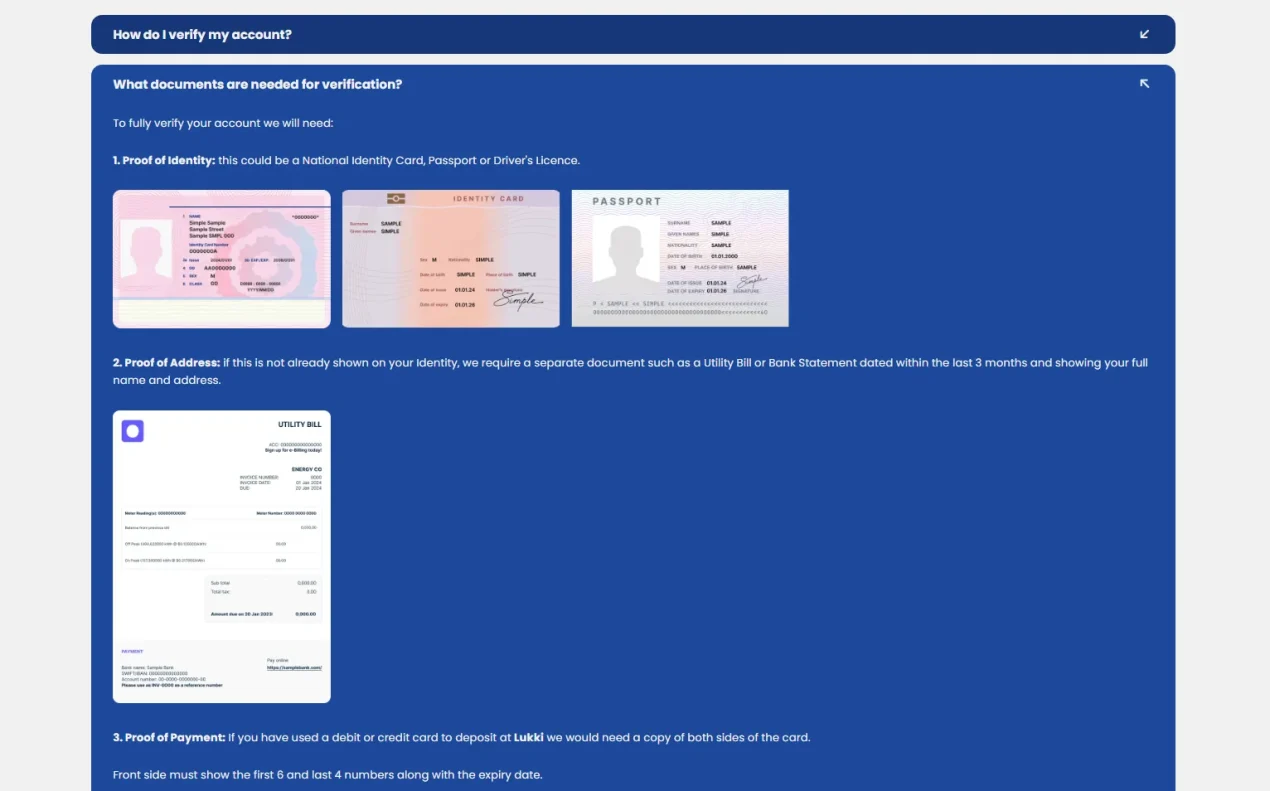
Lukki requires account verification for the first cashout and can request verification at other points for regulatory, security or anti-fraud checks. Its official verification guidance identifies three standard document categories: proof of identity, proof of address where needed and proof of payment for users who deposited by card. The terms also allow further or different documents to be requested when additional checks are necessary.
What is not verified is an exact KYC processing time. A fixed verification time in minutes or hours is therefore not promised. The practical goal is to prepare consistent, readable account evidence, respond to the request shown in your account and use support if the required document or status is unclear. For account creation before KYC becomes relevant, see the account setup guide.
What triggers Lukki verification?
| Situation | Current information | What it means |
|---|---|---|
| First cashout | Verification is required. | Plan for KYC before treating a first withdrawal as ready to process. |
| Security or compliance review | Lukki can request verification at other points. | A check is not limited to the first withdrawal event. |
| Additional verification | Further or different documents can be requested. | The standard document categories are not a guarantee that no other evidence will ever be needed. |
| Exact review time | No guaranteed processing time is stated in the current official information. | Do not plan around an unsupported promise such as instant or same-day KYC. |
The three standard document categories
Lukki’s official verification guidance groups its normal KYC evidence into proof of identity, proof of address and proof of payment for card deposits. These categories explain what the casino is trying to establish: who owns the account, whether the account details are consistent with the user’s address information and whether a card used for funding belongs to the account holder.
- Proof of identity
- This category is used to confirm the identity behind the account. The safe preparation rule is to use a current, readable document that matches the name and other personal details held on the Lukki account.
- Proof of address
- Lukki lists address evidence as a separate category where it is needed. The account details and the submitted evidence should be consistent rather than showing different names or addresses without explanation.
- Proof of payment for card deposits
- Card users can be asked for payment evidence. Treat this as a payment-ownership check and follow the exact privacy and masking instructions shown by Lukki at the time of the request.
No universal upload format, file-size limit or document-review schedule is stated because those details can vary. Those operational details should come from the current verification screen or an account-specific support instruction.
Why first-cashout verification matters
Verification is sometimes treated in casino reviews as an optional profile task, but Lukki’s current guidance makes the first cashout a clear trigger. That changes how a reader should plan the account lifecycle. If identity details are inconsistent at registration, or the payment method is difficult to connect to the account holder, the problem can surface when the user is already trying to withdraw.
The better approach is to think about KYC before the first deposit. Use accurate registration details, keep access to the registered contact channel, use payment methods that can be connected to the account holder and retain the information needed to respond to a later request. That does not make verification instant, but it reduces avoidable mismatches.
Cashout rules themselves belong on the cashout and withdrawal guide. That page covers the verified withdrawal caps and general deposit-wagering rule. Identity and account verification are kept separate from the banking explanation.
Additional verification can happen after a successful check
Lukki’s terms state that further verification procedures can be carried out even after earlier checks have been completed successfully. The terms allow additional, alternative or different documents where the company considers them necessary for regulatory, legal, internal security or anti-fraud purposes.
That means a green status or a previously accepted document should not be interpreted as a permanent guarantee that no future evidence will be requested. A later payment method, changed account information or another security event can create a new verification need.
The useful response is not to upload unrelated documents pre-emptively. Follow the current request shown in the account or sent through the registered communication channel. Supplying extra material that was not requested can make it harder to understand what remains outstanding.
A privacy-minded preparation checklist
- Match the account details. Check that the name and other core information on the account are accurate before uploading identity evidence.
- Use readable evidence. The document should be clear enough for the requested information to be inspected without guessing.
- Use current information. If an address or other account detail has changed, update the account through the proper route rather than submitting conflicting information without context.
- Follow the exact card-masking instructions. If payment proof is requested, use Lukki’s current on-screen guidance and do not expose sensitive card security information beyond what the verification process specifically requires.
- Upload only through the intended verification route. Do not send identity documents to unrelated addresses, third-party review sites or social-media accounts.
- Keep a record of the request. Note which category is outstanding and what the account interface says, so a support conversation can focus on the unresolved item.
- Do not plan around a guessed deadline. The current official material does not establish a guaranteed KYC completion time.
Verification timing
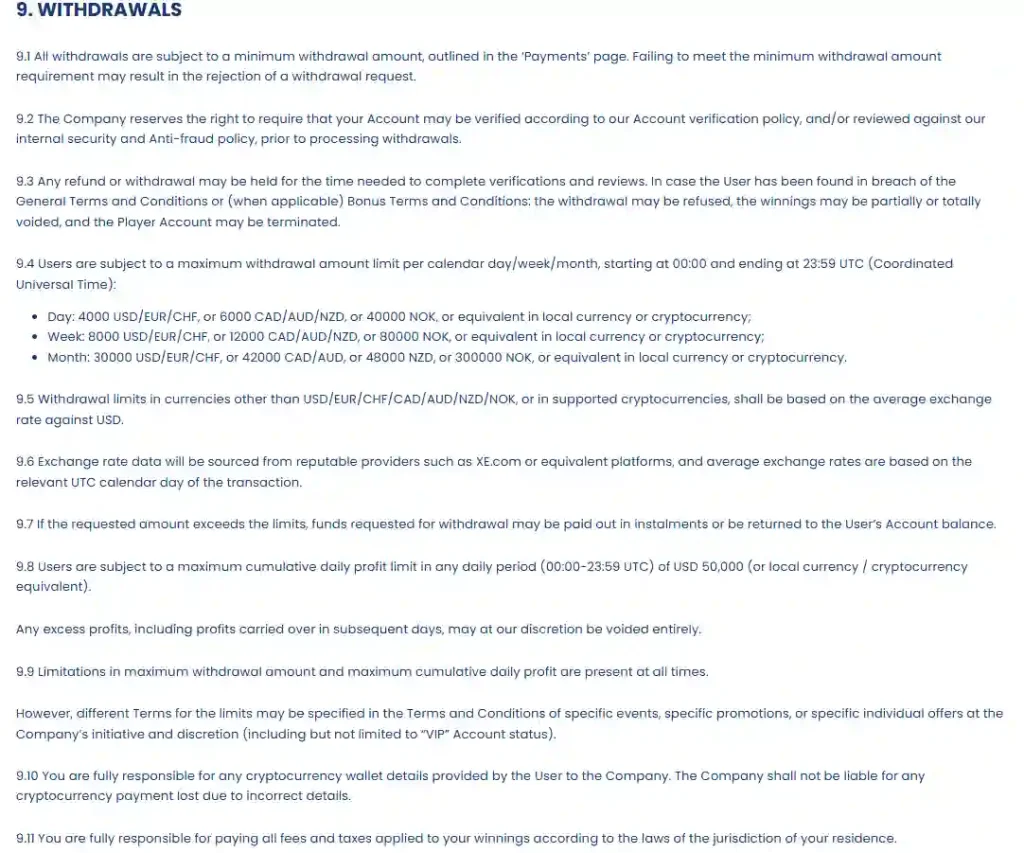
Lukki’s current official material does not state a guaranteed verification processing time. The official verification material explains what is checked and why, while the terms allow withdrawals to be held for the time needed to complete verification and security reviews. Those points explain the process but do not promise that every account will be reviewed within a fixed window.
That distinction is important because casino-review pages often convert user anecdotes or old interface captures into universal timing claims. A fast experience reported by one user is not the same as an official service-level guarantee, and a delayed case does not prove that every verification takes that long.
Verification and account security
Lukki’s general terms frame verification as part of regulatory, legal, internal security and anti-fraud controls. They also allow identification, document and other reviews and require users to cooperate with reasonable information requests. In practice, KYC therefore has a wider role than simply releasing the first cashout.
This is why consistent registration details and payment ownership matter. A name mismatch, an address that has not been updated or a payment method that belongs to another person can turn a routine check into an account-integrity issue. The safest approach is to keep the account internally consistent from the start rather than trying to repair conflicting information at withdrawal time.
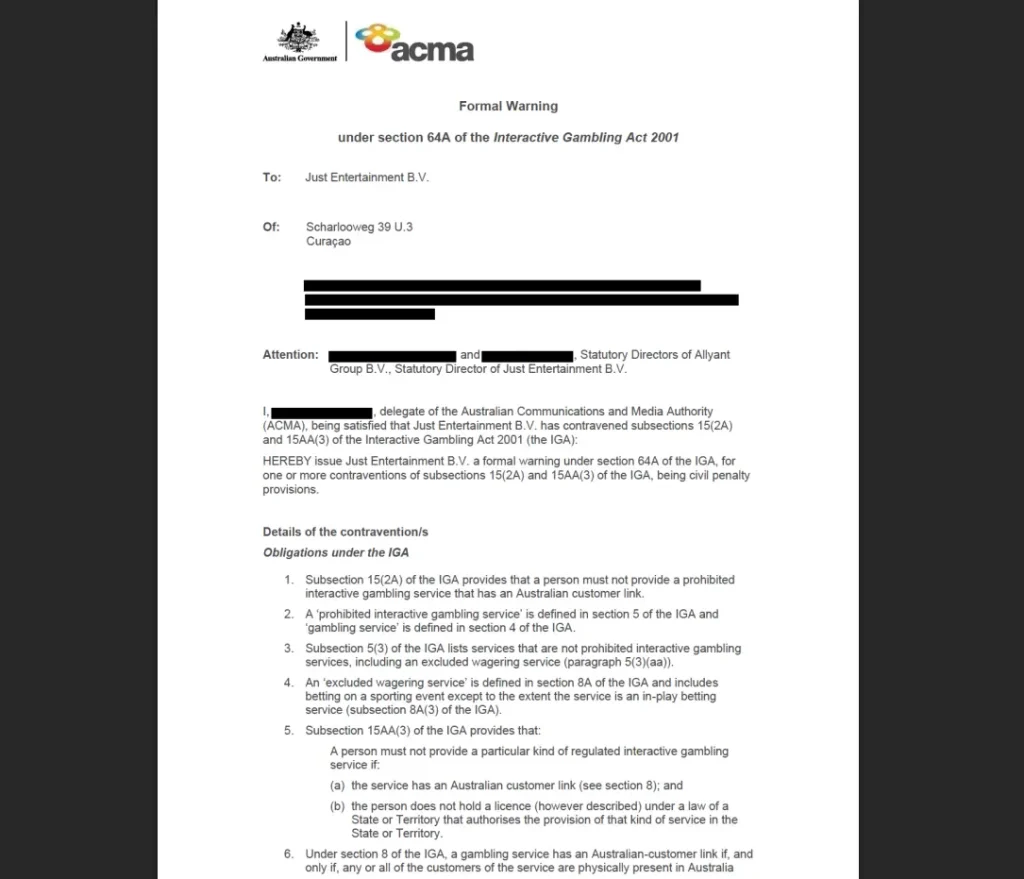
For the broader question of licensing, regulatory history and what protections should not be assumed, use the trust guide. KYC procedures and Australian regulatory authorisation are separate topics and should not be treated as proof of each other.
What to do if a verification request is unclear
Lukki’s official AU support page says customer support is available 24/7. If the verification interface does not make the outstanding document category clear, ask support which requirement remains open and where the document should be supplied. Keep the question account-specific and avoid sending identity documents until you are using the intended secure route.
A useful support message identifies the issue without exposing unnecessary personal data: explain that the account shows an outstanding verification requirement, name the document category if it is visible and ask what current action is required. Do not paste full document numbers, card details or other sensitive information into a general chat message unless the official support process explicitly asks for it in that channel.
If a withdrawal is waiting on verification, separate the two questions. Support can clarify the KYC requirement, while the withdrawal page explains the general cashout rules. That separation helps avoid mistaking a payment limit or wagering issue for an identity-document problem.
Responsible gambling controls connected to account support
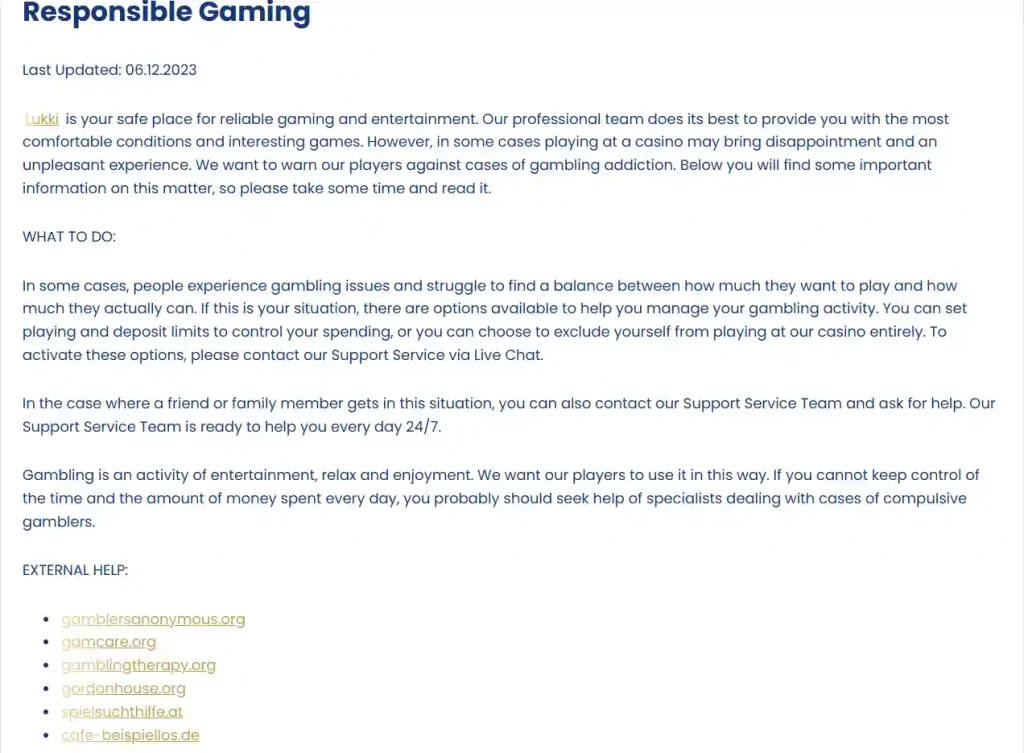
Lukki’s responsible-gaming page says users can request playing and deposit limits through support and can also request self-exclusion through support. These are account-control tools rather than KYC documents, but they are relevant when thinking about how much authority sits behind the account and why secure access matters.
Do not confuse those controls with Australia’s licensed-wagering consumer-protection framework or assume they prove local authorisation. For a broader view of brand-specific safety evidence and reputation signals, see the safety and reputation guide.
Common KYC mistakes to avoid
- Waiting until a first withdrawal to notice inaccurate account details
- Registration information should be correct from the beginning because verification checks it later.
- Assuming one successful check ends all future verification
- Lukki’s terms allow additional verification after earlier checks have succeeded.
- Uploading documents that were not requested
- Use the current verification request as the scope. More files are not automatically better.
- Publishing or sharing sensitive card information unnecessarily
- Follow the current masking instructions and use only the intended secure verification route.
- Expecting a guaranteed completion time
- The current official information does not state a fixed processing time, so a universal promise would be misleading.
- Calling Lukki a no-KYC casino
- That directly conflicts with the verified first-cashout requirement and the terms allowing additional checks.
Bottom line on Lukki verification
The verified core is clear: Lukki requires verification for the first cashout, can request checks at other times and uses proof of identity, proof of address where needed and proof of payment for card deposits as standard document categories. Further documents can be requested where additional checks are required.
The boundary is equally important. The current official material does not establish a guaranteed processing time, so instant, same-day or any other fixed KYC turnaround is not promised. Prepare consistent account information, follow the document request shown in the official interface, protect sensitive data and use 24/7 support when the requirement or status is unclear.
Official references
- Official Lukki AU terms and conditions – verification powers, cooperation requirements and withdrawal review context.
- Official Lukki account verification guidance – first-cashout trigger and standard document categories.
- Official Lukki AU support page – 24/7 support availability.
- Official Lukki AU responsible-gaming page – support-activated playing/deposit limits and self-exclusion.
For the wider brand context, return to the full Lukki review.
This material was created by the Lukki Australia Guide team.
Related posts
Is Lukki Casino Safe? KYC, Support and Reputation Signals
Lukki Casino Licence and Australian Legal Status